Professional Liability vs General Liability for Security Guards, Explained
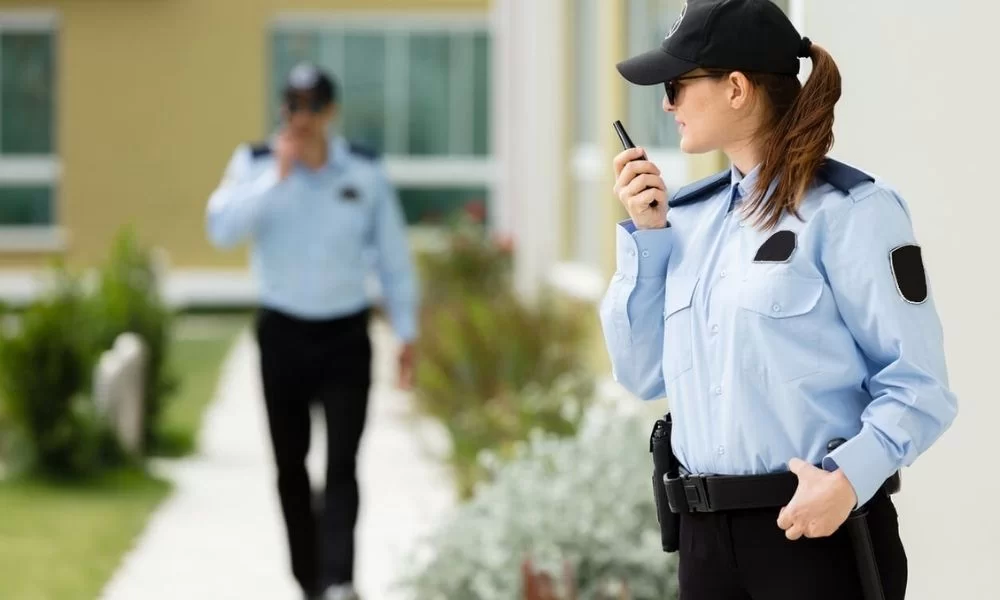
When you run a security business or work as a professional guard, one incident can quickly turn into a legal and financial crisis. A client might claim you failed to prevent a theft, while a bystander could allege they were injured during an altercation. Both situations involve liability, but they fall under very different types of insurance. Understanding the difference between professional liability and general liability is essential for protecting your reputation, your contracts, and your bottom line.
The Big Picture: Why Security Guards Face Unique Risks
Security professionals operate in high-stakes environments where decisions are made in real time. Whether you are patrolling a retail center, managing access at a corporate site, or working event security, you are exposed to both physical and professional risks.
These risks typically fall into two categories:
Physical harm or property damage claims
Claims related to errors, omissions, or failure to perform professional duties
Each category requires a different form of coverage.
What Is General Liability Insurance for Security Guards
General liability insurance protects against third-party claims involving bodily injury, property damage, and certain personal injury allegations that occur as a result of your operations.
What It Typically Covers
A customer slips and falls near a guarded entrance
Property is damaged during a security response
Claims of false arrest, libel, or slander, depending on the policy
This coverage is often required by clients, property managers, and municipalities before you can begin work on a contract.
What It Does Not Cover
General liability does not cover claims related to how well you performed your professional duties. If a client alleges that you failed to prevent a break-in or made a poor judgment call that led to financial loss, this coverage will not apply.
What Is Professional Liability Insurance for Security Guards
Professional liability insurance, sometimes called errors and omissions coverage, focuses on claims tied to the quality of your work and your professional decisions.
What It Typically Covers
Failure to prevent theft or vandalism as outlined in a contract
Alleged negligence in monitoring cameras or access points
Errors in reporting incidents or following procedures
Claims that your professional judgment caused a client financial harm
These claims often involve legal defense costs, even if you did nothing wrong. Professional liability helps cover those expenses and potential settlements.
Why This Matters in Security Work
Many security contracts include performance standards. If a client believes you did not meet those standards, they can pursue legal action for breach of duty or negligence. Without professional liability coverage, you may have to pay legal costs out of pocket.
Key Differences at a Glance
General Liability
Focuses on physical injury and property damage
Covers third-party bodily injury claims
Often required to start or maintain contracts
Professional Liability
Focuses on professional mistakes and service failures
Covers financial losses tied to errors or omissions
Protects against claims related to how you performed your job
Do Security Guards Need Both
In most cases, yes. These two policies are designed to complement each other, not replace one another. A single incident can trigger both types of claims. For example, a physical altercation might lead to a bodily injury claim under general liability and a negligence claim under professional liability.
Having both policies creates a more complete risk management strategy and can make your business more attractive to higher-value clients who require comprehensive coverage.
How Much Coverage Is Enough
Coverage limits depend on the size of your operation, the types of sites you protect, and the contract requirements of your clients. Large commercial properties and government contracts often require higher limits for both policies.
Working with an agency that understands the security industry can help you avoid underinsuring or paying for unnecessary coverage.
Getting the Right Guidance
Insurance for security professionals is not one-size-fits-all. Policy language, exclusions, and endorsements can vary significantly between carriers. Agencies like JPL Insurance Services focus on helping security businesses evaluate their operational risks and align coverage with real-world exposures, rather than just meeting minimum contract requirements.
Final Thoughts
Professional liability and general liability insurance serve two very different but equally important roles in protecting security guards and security companies. One shields you from claims tied to physical incidents, while the other protects you from allegations about how well you performed your professional duties. Together, they form a strong foundation for long-term stability, client confidence, and business growth. If you are unsure whether your current policies truly cover the full range of risks you face, a thoughtful review with JPL Insurance Services can help you move forward with clarity and confidence.